
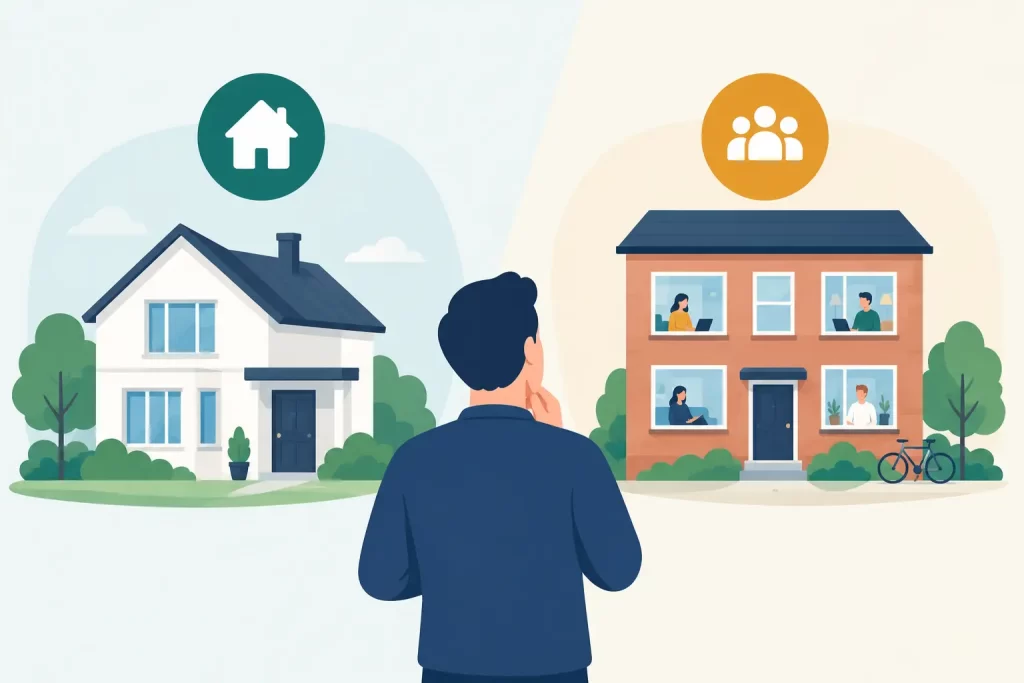
A single-family rental can feel like the sensible first step. An HMO can look like the faster route to cash flow. Neither is automatically the better investment.
The real buy to let versus HMO decision comes down to your goals, available capital, appetite for management, and ability to operate the property properly. Choose based on headlines or a promised yield alone, and you can end up with an asset that consumes your time, cash, and confidence. Choose based on a clear strategy, and either model can become a valuable part of a growing portfolio.
For UK investors, this is not simply a comparison between one tenant and several tenants. It is a comparison between two different property businesses.
Buy to Let Versus HMO: The Core Difference
A traditional buy-to-let property is typically let to one household on one tenancy. That might be a couple, a family, or a group renting jointly. Income is straightforward: one rent payment each month, usually supported by a single tenancy agreement and a simpler management process.
An HMO, or house in multiple occupation, is occupied by people from more than one household who share facilities such as a kitchen, bathroom, or living area. In practice, many investors use the term to describe a shared house let by the room to working professionals or students. Each room can produce income, which creates a very different financial profile from a standard rental.
That difference is attractive, but it brings more moving parts. An HMO can require licensing, planning consideration, fire safety measures, more intensive tenant management, stronger systems, and a larger upfront budget. A buy-to-let property is usually easier to understand operationally, though it is not free from regulation, maintenance, or void periods.
Start With the Outcome You Want
Before comparing spreadsheets, decide what the property needs to do for you. If you want a relatively hands-off asset that may suit long-term tenants and simpler management, a standard buy to let may fit. If your priority is stronger monthly cash flow and you are prepared to run a more active operation, an HMO may deserve serious attention.
Your stage of investing matters too. A first-time investor might benefit from learning how to source, finance, refurbish, and manage a conventional rental before taking on a more complex shared house. But that is not a rule. With the right education, professional team, and clear plan, some investors begin with an HMO because its income better supports their financial goals.
The question is not, “Which strategy is best?” It is, “Which strategy can I execute well, repeatedly, and profitably?”
Income: Why HMOs Can Produce More Cash Flow
The main appeal of an HMO is multiple income streams. Instead of relying on one household to pay a single monthly rent, you might receive rent from four, five, or six rooms. If one tenant leaves, the whole property is not necessarily empty.
That can create stronger gross income and, in the right area, stronger net cash flow after costs. It can also make an HMO more resilient to a single vacancy. A traditional buy to let, by contrast, has one rental income source. When that tenant leaves, your rental income can drop to zero until the next tenancy starts.
But gross rent is not profit. HMOs commonly carry higher utility bills, council tax liability, broadband costs, cleaner costs for communal areas, licensing fees, more frequent repairs, furnishing costs, and greater management fees if you outsource. Tenant turnover can also be higher, particularly in student markets or areas with transient professional renters.
A conventional rental can deliver lower income but cleaner operations. One well-maintained property with reliable tenants and limited turnover may produce a return that is easier to forecast. Your deal analysis must include every operating cost, a maintenance allowance, realistic void assumptions, and finance costs. Do not let a high headline HMO rent persuade you to skip the hard numbers.
Upfront Costs and Financing
A standard buy-to-let purchase usually has a lower barrier to entry. The property may need cosmetic work, safety compliance, and furnishing depending on your tenant profile, but the conversion scope is often modest compared with an HMO.
An HMO may need substantial work before it is ready to let. Room sizes, fire doors, alarms, emergency lighting, escape routes, soundproofing, bathroom provision, kitchen layout, and amenity standards can all affect the project. Requirements vary between local authorities, so a property that works as an HMO in one area may not be viable in another.
Financing can be more specialized as well. Lenders assess HMOs differently, and their criteria may depend on the number of rooms, whether the property is licensed, your experience level, and projected rental income. If you plan to refinance after a refurbishment or conversion, understand the lender’s valuation approach before you commit. Your exit should be tested before you exchange contracts, not invented afterward.
This is where investors can get caught out. They budget for the purchase and basic renovation, then discover that compliance work, planning issues, or a lower-than-expected valuation have tightened the deal. Build contingency into your numbers. A deal needs room for reality.
Management Is the Deciding Factor for Many Investors
A buy to let can still demand attention, especially when repairs arise or tenants change, but it is generally less management-heavy than a shared house. One household means fewer relationships to manage, fewer contracts, and less wear in shared spaces.
An HMO is a hospitality-style property business as much as an investment. You are managing tenant expectations, room advertising, viewings, references, move-ins, inspections, maintenance requests, and the dynamics of people sharing a home. High standards are not optional if you want to attract good tenants and protect your reputation.
You can appoint a managing agent, but outsourcing does not remove your responsibility as the owner. You still need to understand compliance, monitor performance, and ensure the agent is delivering. The strongest HMO investors put systems in place early: clear tenant criteria, detailed inventories, responsive maintenance processes, regular inspections, and a reserve fund.
Ask yourself honestly how much time you can give the property. If you have a demanding career or family commitments, a standard rental or a professionally managed HMO may be the right route. If you enjoy operations and want to build a high-cash-flow portfolio, an HMO can be worth the extra effort.
Regulation and Location Can Make or Break the Deal
With HMOs, local knowledge is essential. Mandatory licensing applies to certain larger HMOs, while many councils operate additional or selective licensing schemes that capture smaller shared houses. Planning rules, including Article 4 directions, can restrict a change from a family home to an HMO in specific areas.
Never assume that a property can become an HMO because similar houses nearby appear to be shared. Check the local authority’s licensing standards, planning position, parking expectations, waste storage requirements, and space standards. Speak with experienced local professionals, but verify the facts yourself.
Traditional buy to lets have their own regulatory responsibilities, from gas safety and electrical safety to deposit protection and energy efficiency requirements. They are simpler in many cases, not risk-free. Good investors treat compliance as part of the business plan, not a last-minute checklist.
Location also changes the answer. In an area with strong demand from young professionals, hospitals, universities, or major employers, an HMO may perform well. In a family-led area where tenants want gardens, schools, and long stays, a standard buy to let may be the stronger choice. Demand should lead your strategy, not the other way around.
How to Make the Right Choice
Run both models against the same property where possible. Estimate the purchase price, refurbishment budget, financing costs, achievable rents, operating costs, voids, and contingency. Then test what happens if interest rates rise, a room sits empty, or the renovation costs more than planned.
A buy to let may win because it gives you dependable income with less complexity. An HMO may win because its higher net cash flow helps you replace income, reinforce borrowing capacity, or grow your portfolio faster. There is no prize for choosing the more complicated strategy. The win is acquiring a property that moves you closer to your stated financial target.
If you are unsure, get support before committing. A mentor-led review can challenge your assumptions, expose gaps in the numbers, and help you assess whether the property fits your wider plan. At Property Master Academy, the focus is not on pushing investors toward one model. It is on helping you build the knowledge and confidence to make decisions you can stand behind.
The best next move is not to chase the highest advertised yield. Choose a strategy, learn the operational reality, and take action only when the deal works on paper and still makes sense when real life happens.